In 2022, the California Department of Insurance put into effect a regulation that requires insurers to recognize wildfire safety actions in their pricing. The framework behind it is called Safer from Wildfires, developed with state emergency and fire agencies.
The idea is simple. If you reduce your home's risk in specific, proven ways, your insurer has to account for it.
The three levels
Safer from Wildfires recognizes mitigation at three scales:
- Community. Neighborhoods that participate in programs like Firewise USA or are recognized as Fire Risk Reduction Communities.
- Property. The immediate surroundings of the home, including defensible space and the ember-resistant zone.
- Structure. The building itself: roof, vents, windows, eaves and the base of exterior walls.
Property and structure actions
The property-level and structure-level list includes actions such as:
- A Class A fire-rated roof
- A five-foot ember-resistant zone around the home, including fencing
- Six inches of noncombustible vertical clearance at the base of exterior walls
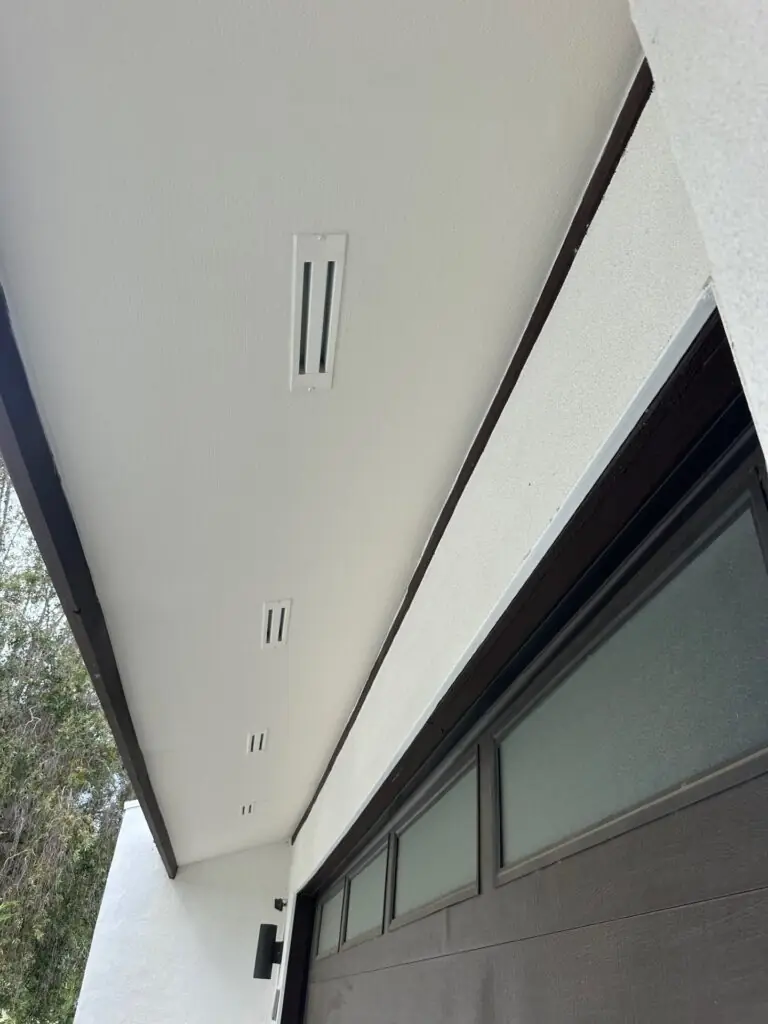
- Ember- and fire-resistant vents
- Upgraded windows, or added protection for existing glass
- Enclosed eaves
- Cleared vegetation and debris under decks
- Compliance with state and local defensible space requirements
Check the Department of Insurance's current materials for the full and latest list, since programs are updated over time.
How Wetline maps to the list
| Safer from Wildfires area | Wetline layer |
|---|---|
| Ember-resistant vents | Vents and gutters |
| Five-foot ember-resistant zone | Pre-treatment and landscape plan |
| Window protection | Window laminates |
| Eaves and wall base | Fire-retardant paint and enclosure work |
| Beyond the list | Autonomous sprinklers and 24/7 monitoring |
Some of what we install, like sprinklers and monitoring, goes beyond the state's list. Those layers may not earn a specific discount, but they add protection and strengthen the overall picture a broker presents to an underwriter.
Documentation is the difference
Insurers can only credit what they can verify. Our readiness report lists each mitigation with photos and specifications, organized against the Safer from Wildfires categories, so your broker isn't guessing.
Tip. Ask your insurer or broker how they verify mitigation. Some accept homeowner documentation, some use inspections, and some rely on third-party designations like the IBHS Wildfire Prepared Home.
The bottom line
Safer from Wildfires gives homeowners leverage. It doesn't set a fixed discount, and results vary by carrier. But it does mean the work you do on your home can't simply be ignored. Start with a free assessment to see which actions your home already meets and which are worth doing next.
Frequently asked questions
Does Safer from Wildfires guarantee a discount?
It requires insurers to recognize qualifying mitigation in their rates, but the size of any discount varies by carrier.
Do I need all the mitigation actions to qualify?
No. Insurers recognize individual actions, though more actions generally means a stronger risk profile.
How do I prove my home qualifies?
Keep photos, invoices and product specifications. A Wetline readiness report organizes this against the Safer from Wildfires categories.