- Home
- Insurance
Hardening is how fire-country homes get insured.
Carriers are writing policies again for homes that can prove their defenses. We do the work and build the file your broker needs.
[ 01 ]Three ways hardening helps
Better risk. Better options.
Wetline is not an insurance agent. We make your home a better risk and prove it on paper.
Placement
Hardened, documented homes give brokers a case for admitted carriers instead of fallback coverage.
Premium
Mitigation discounts and a move off the FAIR Plan can lower total premium, sometimes enough to repay the work.
Renewal
Maintenance logs keep your documentation current and help protect against non-renewal.
[ 02 ]Insurance guides
Understand your options.
 →Guide
Leaving the FAIR Plan
A step-by-step path from fallback coverage back to the admitted market.
 →Guide
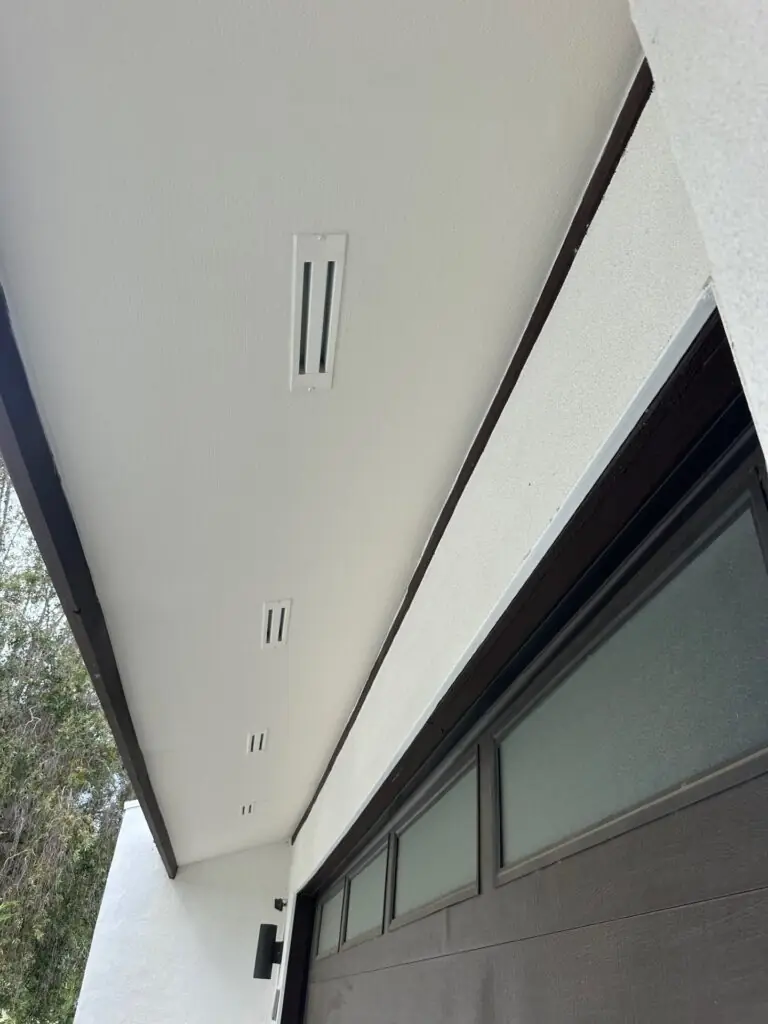
Safer from Wildfires
California's list of mitigations insurers must recognize, and how to qualify.
 →Guide
Wildfire Prepared Home
The insurance industry's own designation and what it takes to earn it.
 →Guide
Nevada and Tahoe coverage
How Sierra underwriting works and what Tahoe insurers look for.
[ 03 ]Run your numbers
Two minutes. Real estimates.
[ ? ]FAQ
Insurance questions.
Still deciding? Call or text 310-569-4523.
Can home hardening lower my insurance in a high fire zone?
Often, yes. California requires insurers to recognize qualifying wildfire mitigation, and many carriers will write or renew a hardened home they would otherwise decline. Our clients have placed with standard carriers after hardening, and some recover the full cost of the work in premium savings within about five years. Your carrier sets final pricing.
I'm on the FAIR Plan. Can Wetline help me get off it?
That's one of the most common reasons people call us. We harden the home, then give you a readiness report that lists each mitigation in the terms carriers use, so your broker can shop the standard market with evidence in hand.
Is Wetline an insurance company or agent?
No. We are a licensed contractor. We do the work and document it, and your broker or agent shops coverage.
What goes in the readiness report?
Each mitigation we install or verify, with photos, product ratings, vent mesh sizes, glazing protection, water supply and maintenance logs.