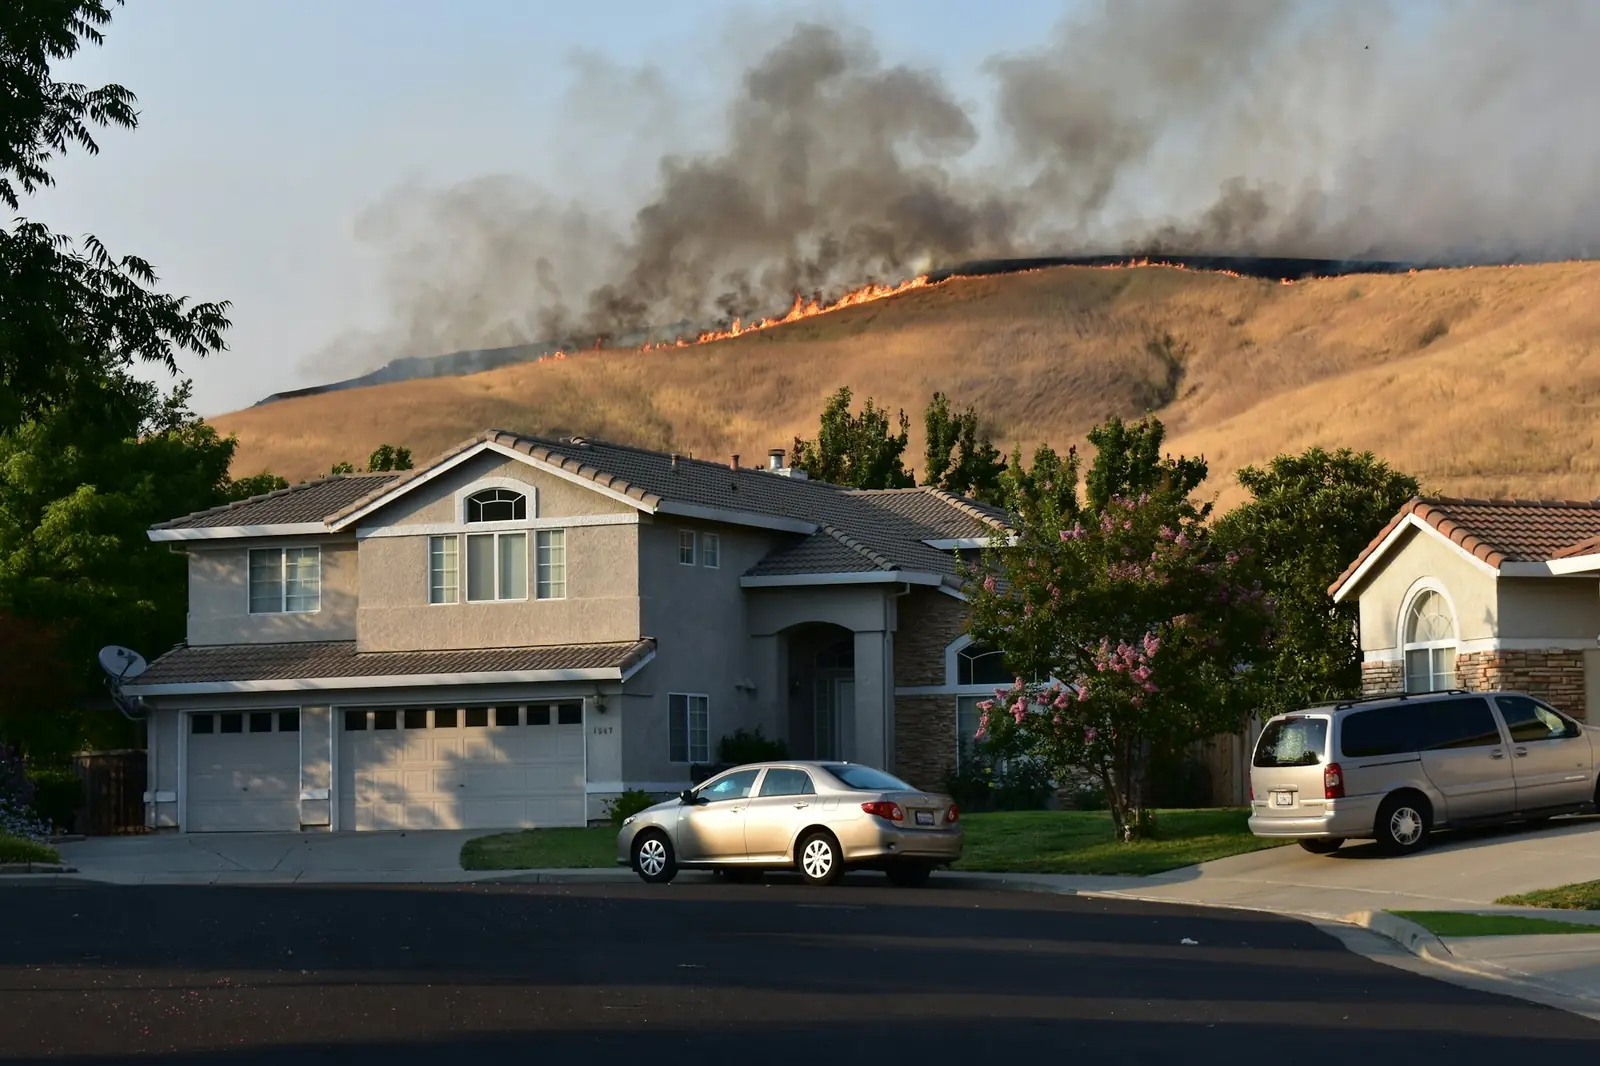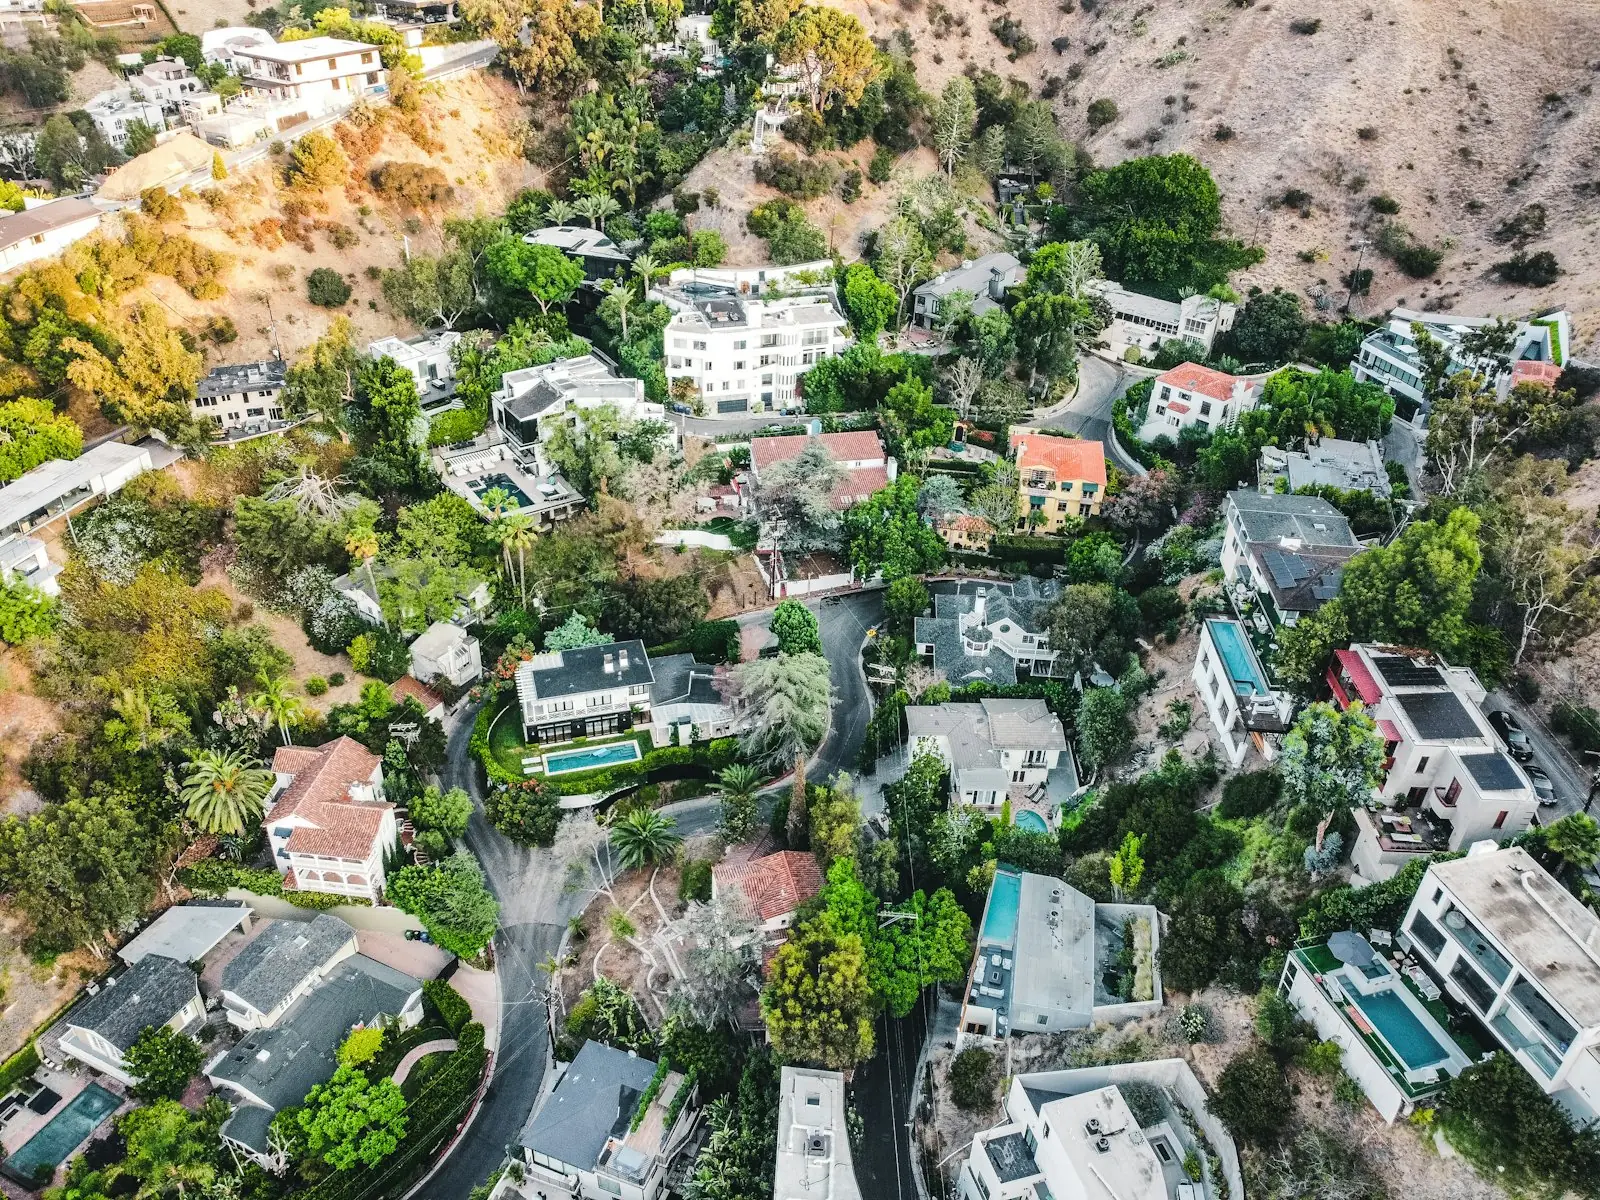
California FAIR Plan rates rose an average of 29.1% on October 15, 2026. The increase affects more than 675,000 policyholders, many of them in high fire-risk hillside and canyon communities. For some homeowners in the riskiest areas, the wildfire portion of the premium could roughly double.
What changed
The California Department of Insurance approved the 29.1% average increase, lower than the 35.8% average the FAIR Plan originally requested. The change applies as policies renew. Amounts vary widely by location and wildfire risk. Lower-risk urban areas may see smaller increases, and some may see reductions.
Why rates went up
The FAIR Plan is California's insurer of last resort, an association of licensed insurers designed to provide basic fire coverage to homeowners who cannot get it elsewhere. It was never meant to be permanent coverage, but enrollment has grown from under 2% of California homes to about 5%.
Reports on the increase point to several pressures:
- Exposure. FAIR Plan exposure reached roughly $768 billion as of June 2026, up 11% since September 2025 and about 250% higher than September 2022.
- Thin reserves. Estimated cash reserves of $200 million to $400 million are small compared with that exposure.
- Large losses. Claims from the January 2025 Los Angeles County fires were substantial.
- Costs. Construction costs keep rising, and a Stanford University study released in June 2026 found homeowners insurance premiums have risen 84% since 2020.
A sign of easing
There is some good news. New FAIR Plan business in 2026 is reportedly down about 25% from last year, and regulators suggest the state's Sustainable Insurance Strategy may be encouraging private insurers to return to the market. As more admitted carriers write policies again, homeowners have a better chance of moving off the FAIR Plan.
Carriers coming back are selective. They are looking for homes that are a better risk, and for proof.
How hardening helps
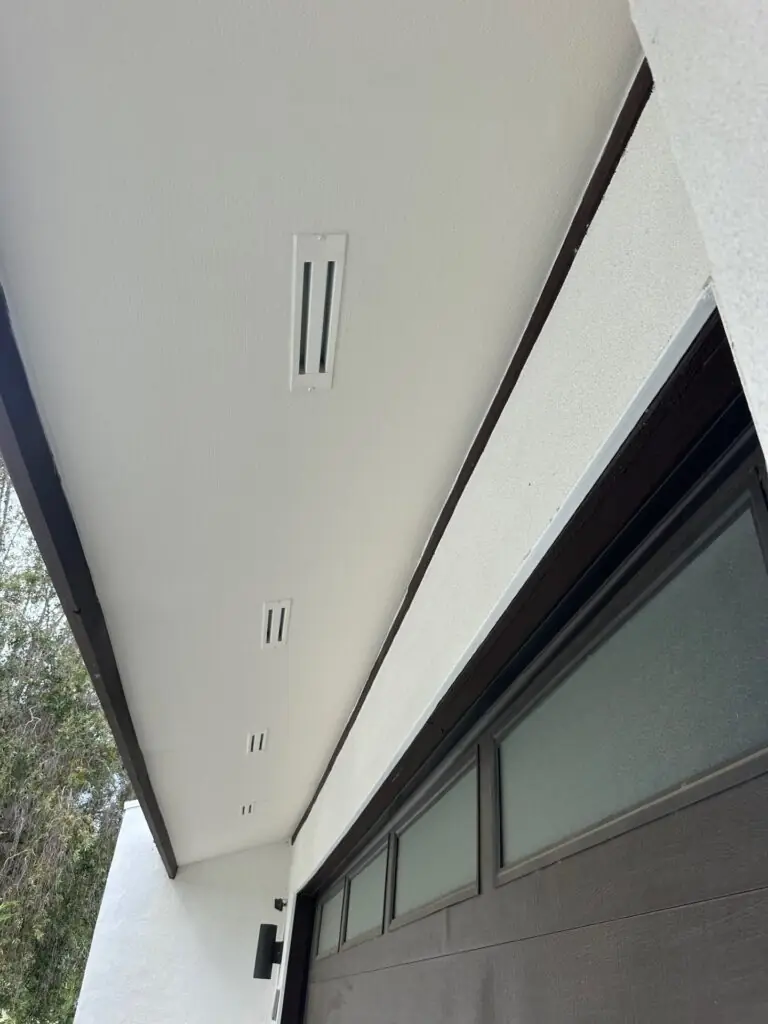
California requires insurers to recognize qualifying wildfire mitigation under the Safer from Wildfires framework, including a Class A roof, ember-resistant vents, enclosed eaves, multi-pane windows and cleared defensible space. Insurers that offer discounts must factor these in. The industry's Wildfire Prepared Home designation from IBHS goes further and is recognized by a growing number of carriers.
At Wetline, we have seen hardened, well-documented homes placed with admitted carriers instead of renewing on the FAIR Plan. Results depend on the home, the carrier and the market, but the documentation gives your broker something concrete to work with. Our step-by-step guide to getting off the FAIR Plan walks through the process.
What this means for your home
- Read your renewal notice. Check the new premium and coverage limits, and compare them with what it would cost to rebuild today.
- Ask about a difference-in-conditions (DIC) policy. The FAIR Plan covers fire and a few other perils. A DIC policy fills gaps like liability and theft. Our FAIR Plan vs. standard policy guide explains the difference.
- Harden the high-impact items first. Vents, roof, gutters and the first five feet usually matter most to underwriters.
- Get it documented. Photos, invoices and an assessment report in underwriting language help your broker shop for admitted coverage.
- Run your numbers. The Find Savings tool estimates your readiness score and what hardening could mean for your premium.
Frequently asked questions
When does the FAIR Plan rate increase take effect?
The average 29.1% increase took effect October 15, 2026, and applies as policies renew. The amount for any home depends on its location and wildfire risk.
Can I leave the FAIR Plan?
Yes, if an admitted carrier will write your home. Hardening your home and documenting the work improves your chances. Work with a broker who knows the fire-zone market.
Do FAIR Plan policies give mitigation discounts?
California's Safer from Wildfires regulations require insurers that offer discounts to recognize qualifying mitigation. Ask the FAIR Plan and your broker which credits your home qualifies for.
Sources
- California FAIR Plan rates to jump nearly 30% in October, Los Cerritos Community News (Aug. 17, 2026)
- California FAIR Plan rates jump nearly 30% as homeowners seek wildfire insurance alternatives, Patch (Oct. 16, 2026)
This article is general information, not insurance or legal advice. Your carrier sets final pricing and eligibility.